No-cost EMI is not interest-free. The bank still charges interest, but the store or brand gives you a discount equal to that interest, so your EMIs add up to the product price.
Read more
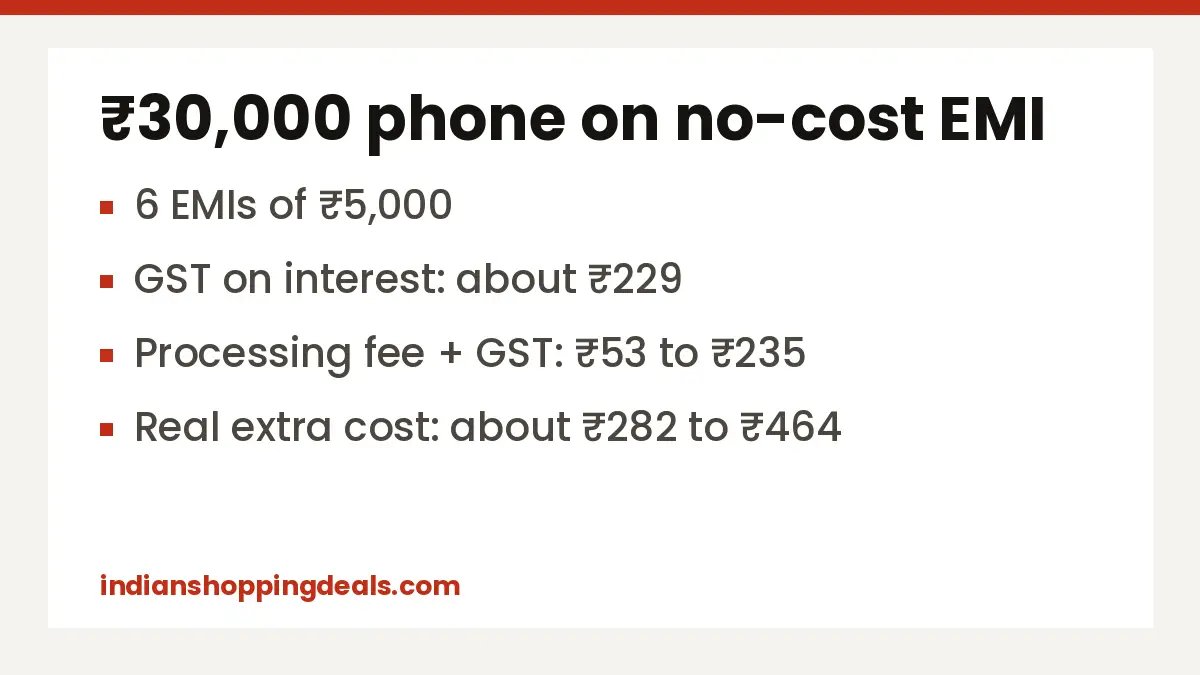
What you do pay extra is 18% GST on the interest and, with many banks, a processing fee. On a ₹30,000 phone over 6 months that is roughly ₹250 to ₹500 extra. It is worth it if you would otherwise pay in full from savings you need, and not worth it if you plan to close the EMI early or if choosing EMI costs you a bigger discount.
| Item | What happens | Who sets it |
|---|---|---|
| Interest | Charged by the bank, offset by an upfront discount | Bank rate, discount by store or brand |
| GST on interest | 18% on the interest part of each EMI | Law; shown on card statement |
| Processing fee | One-time fee, plus GST; varies by bank. SBI Card: nil for 3 months, ₹45 for 6 months on bookings of ₹20,000+ from 10 Sept 2026 | Bank |
| Credit limit | Full price blocked on day one, released as you pay EMIs | Bank |
| Foreclosure | Fee on the outstanding amount. SBI Card: 3% plus tax | Bank |
| Cashback and reward points | Usually none on EMI (Axis Flipkart card, SBI Card Merchant EMI) | Bank |
| Return or exchange | Interest already charged usually not refunded | Flipkart payments page, SBI terms |
How no-cost EMI really works
EMI means Equated Monthly Instalment: you pay a fixed amount every month for a set number of months. With a normal EMI you pay the price plus interest. With no-cost EMI, the store or the brand pays the interest for you, by giving a discount at checkout.
Here is the mechanism in plain words. The phone costs ₹30,000. The bank wants about 15% a year interest. So the store knocks off exactly the amount of interest the bank will charge, about ₹1,270. The bank lends you the remaining ₹28,730, charges its interest on that, and your six EMIs come to ₹5,000 each. ₹5,000 × 6 = ₹30,000, the same as the price. That is why it looks free.
Business Today described it the same way: interest of 15 to 20% is charged but offset with a matching discount. Flipkart’s payment page also reminds buyers that the full amount is charged on your card on the day of the transaction, and the bank then splits it into instalments.
Worked example: ₹30,000 phone, 6 months
Assume a 15% yearly interest rate (banks set their own rate) and SBI Card’s processing fee for a 6-month Merchant EMI booked from 10 September 2026.
| Line | Amount |
|---|---|
| Phone price | ₹30,000 |
| No-cost EMI discount (equal to interest) | – ₹1,270 |
| Loan amount billed as EMI | ₹28,730 |
| EMI per month × 6 | ₹5,000 × 6 = ₹30,000 |
| Interest inside those EMIs | ₹1,270 (₹359, ₹301, ₹242, ₹183, ₹123, ₹62) |
| 18% GST on interest | about ₹229 |
| Processing fee ₹45 + 18% GST | about ₹53 |
| Total you pay | about ₹30,282 |
| Extra over paying ₹30,000 in full | about ₹282 |
With a bank that charges a ₹199 processing fee (Business Today says ₹100 to ₹1,000 is common), the extra would be about ₹464. Still small, but it is not zero, and it shows on your statements as separate lines, which surprises many first-time buyers.
Add the sale bank offer
During the sales, the bank’s 10% instant discount often works on EMI too. Amazon says the 2026 SBI offer covers credit card EMI. Last year SBI’s cap on EMI orders was higher than on full payment (₹1,750 vs ₹1,500 on most categories). On our ₹30,000 phone, a ₹1,750 EMI discount brings the price down to ₹28,250 before the EMI is worked out. Check that the payment page shows both the bank offer and the no-cost EMI discount.
Your credit limit is blocked for the full amount
SBI Card’s terms say the credit limit is blocked for the full transaction amount and released as each EMI is billed and paid. So on a card with a ₹50,000 limit, a ₹30,000 EMI leaves only ₹20,000 to spend in month one. If you plan to buy more in the same sale, keep this in mind. A high used limit can also lower your credit score for a while because of higher credit use.
What happens if you close the EMI early
Foreclosure means paying off the rest of the loan in one go. It sounds smart, but on no-cost EMI it usually costs you. The interest discount was already given in full at the start, while the fee is charged on what is left.
| Close after 2 EMIs (SBI Card example) | Amount |
|---|---|
| EMIs already paid | ₹10,000 |
| Outstanding principal | about ₹19,390 |
| 3% foreclosure fee + 18% GST | about ₹687 |
| GST on 2 months interest + processing fee | about ₹172 |
| Total paid | about ₹30,249 |
You pay about ₹249 more than the ₹30,000 price, mostly because of the foreclosure fee. SBI’s terms also say there may be interest debits or credits depending on when you ask, so the bank’s final number can differ a little. The processing fee is reversed on cancellation but not on foreclosure. If you know you will have the money in two months, paying in full or choosing a 3-month EMI with no fee is cheaper.
If you return the product
Flipkart says interest charged by the bank till the return will not be refunded by Flipkart. SBI Card cancels a Merchant EMI automatically only if the full refund arrives within 45 days, in one go, for the same amount and with the same authorisation code. Partial refunds do not cancel the EMI. See our refund guide for the steps.
Debit card EMI and Pay Later
Debit card EMI
Some banks offer pre-approved EMI on debit cards to selected customers. It is a small loan from your bank, so it carries interest, fees and a credit record like any loan. In last year’s Big Billion Days terms, ICICI debit cards got the 10% offer only on EMI, not on full payment. Amazon says SBI debit cards are part of its 2026 offer.
Pay Later
Amazon says Amazon Pay Later gives 10% cashback on a range of purchases and Pay in 3 interest-free EMIs on carts of ₹1,500 and above with zero processing fee during the 2026 festival. Pay Later is also credit. Miss a payment and you pay late fees and harm your credit score.
When no-cost EMI is worth it
- Yes when you need the product now, you have the income to cover each EMI, and the extra cost (GST and fee) is a few hundred rupees.
- Yes when the bank’s sale offer is bigger on EMI than on full payment, as SBI’s was last year.
- No when you would close it early, since the foreclosure fee eats the benefit.
- No when the card gives cashback on full payment but not on EMI. On the Flipkart Axis card, 5% cashback on a ₹30,000 order is ₹1,500, far more than you save by spreading payments. Axis excludes EMI from cashback.
- No when the “no-cost” tenure is short but you pick a longer one. Longer tenures often carry real interest.
- Never for things you would not buy if you had to pay in full.
Use our sale bank offer calculator to compare, and read instant discount vs cashback before choosing.
Questions people ask
Is no-cost EMI really free?
Not fully. Interest is covered by a discount, but you still pay 18% GST on the interest and often a processing fee. On a ₹30,000 order that is usually a few hundred rupees.
Why is GST charged on no-cost EMI?
Because the bank still charges interest on the loan, and GST applies to that interest. The discount offsets the interest, not the tax.
Is there a processing fee on no-cost EMI?
Many banks charge one. SBI Card charges nil for 3 months and ₹45 plus tax for 6 months on Merchant EMI bookings of ₹20,000 and above from 10 September 2026. Other banks charge more.
Can I close a no-cost EMI early?
Yes, but you pay a foreclosure fee. SBI Card charges 3% of the outstanding amount plus tax, which usually wipes out any benefit.
Does no-cost EMI block my credit limit?
Yes. The full amount is blocked on day one and released as you pay each EMI.
Do I get cashback on no-cost EMI?
Usually not on co-branded cards. Axis excludes EMI from Flipkart card cashback, and SBI Card gives no reward points on Merchant EMI.
Is debit card EMI a loan?
Yes. It is a pre-approved loan from your bank with its own interest and fees, even if the store calls it no-cost.
Sources
- SBI Card: Merchant EMI and Convert2EMI terms (processing fee, foreclosure, GST, credit limit)
- Flipkart: Payments help page (EMI)
- About Amazon India: Great Indian Festival 2026 (SBI EMI offer, Amazon Pay Later)
- ICICI Bank: Flipkart offer terms (Big Billion Days 2025)
- SBI Card: Amazon.in festive offer terms (September 2025)
- Axis Bank: Flipkart Axis Bank Credit Card cashback terms
- Business Today: Is no cost EMI really cost free? (October 2025)
- Business Today: No cost EMI explained, myths and hidden charges (December 2025)